Email alerts on options metrics, plus two daily emails
This page describes GEXStream's metric email alerts: per-ticker rules over the screener metrics, covering gamma exposure (GEX), GEX by volume (vGEX), options flow, implied volatility (IV) and open interest (OI), plus spot price, that send an email when a condition becomes true during the regular session. It also covers the two daily subscriber emails, Premarket Movers and Close Screen, and their opt-out switches.
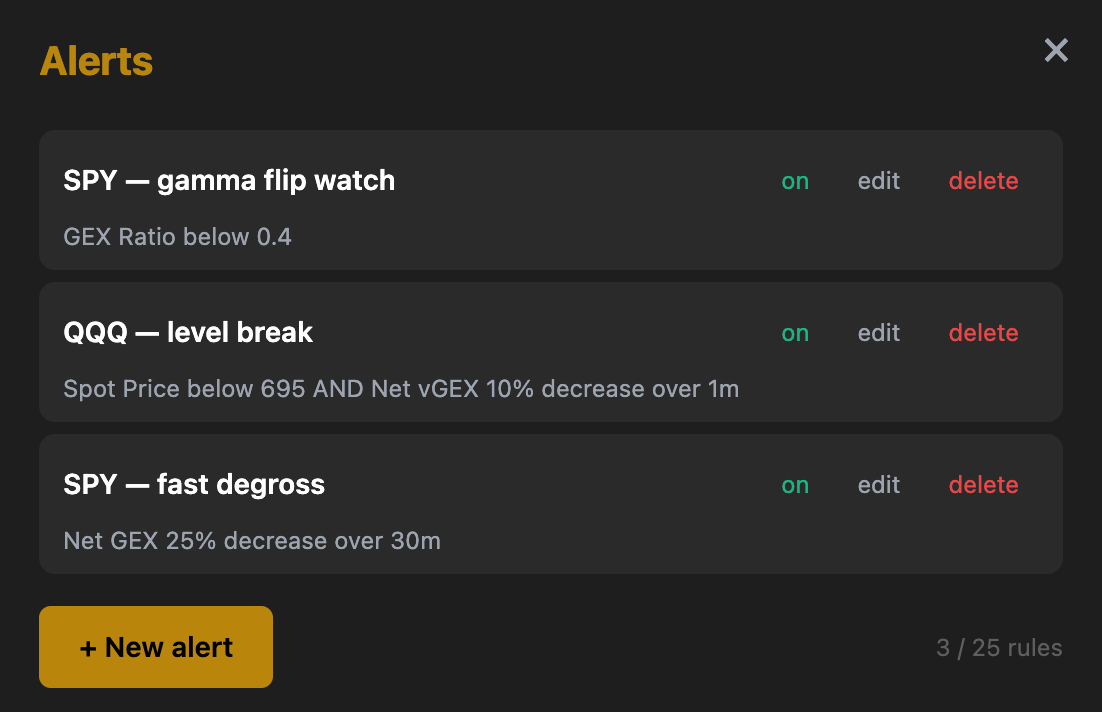
What it shows
A rule names one ticker from the tracked universe, one to five conditions, and whether they combine with AND or OR. The metrics are the ones the Pulse screener shows: Spot Price, GEX Ratio and Net GEX, vGEX Ratio and Net vGEX, Flow Ratio and Net Flow, Net IV and Net IV Chg, OI Ratio, Total OI and OI Chg%. Quant adds the delta exposure (DEX), vanna exposure (VEX) and charm exposure (CEX) ratios and net values, plus Net Premium and Premium Ratio. Net Convexity is not an alert metric yet.
- Threshold: the metric above or below a value. The ratios run from 0 to 1, so a threshold on them means the same thing on every ticker.
- Change over a window: a percent rise or fall over 1, 5, 15 or 30 minutes, or a point change on the 0-to-1 ratios. The baseline must come from the same session: an overnight gap is not a 30-minute move, so a window reaching into the prior session is treated as unavailable. The open interest metrics and Net IV Chg take no change window: open interest settles overnight, and OI Chg% and Net IV Chg are already day-over-day readings.
- Z-score: the live value in standard deviations from that ticker's own 120-day band, offered only on the unbounded metrics (Net GEX, Net Flow, Net IV, Net vGEX, Net DEX, Net VEX, Net CEX, Total OI and Net Premium). The band is the one behind the dashboard sigma badge, so a rule at 2 sigma fires exactly when that badge turns red.
How to read it
The alerts section of the docs gives the short version: bounded metrics read best as thresholds, unbounded ones as z-scores, AND for confluence (spot below a level and Net vGEX down 10% in 15 minutes), OR to watch both tails of one metric. Each metric's formula lives in its own docs section, such as GEX or DEX, VEX and CEX. Note that DEX, VEX and CEX sum call and put exposure at natural sign, so their sign describes the positioning of the options, not a dealer's book.
The email names the ticker and rule in its subject and shows each condition's live value, with the earlier value and change for a windowed condition and the sigma against the 120-day band for a z-score.
Cadence, edge-triggering and cooldowns
Every rule is checked every 30 seconds during regular hours, 9:30 AM to 4:00 PM ET on trading days, ending at the early close on shortened days. Emails leave a queue at about one per second, and one account can receive at most 50 alert emails in a day.
Rules are edge-triggered: a rule fires when its conditions turn from false to true, and re-arms only once they clear. A cooldown then bounds the rest: 5, 15, 30, 60, 120 or 240 minutes, or once a day, meaning once per ET trading session rather than a rolling 24 hours. A crossing inside a cooldown is consumed, not deferred.
Flow accounts can keep 10 rules and Quant accounts 25, each with up to five conditions. Any rule can be muted without being deleted.
The seeded example
The first time a Flow or Quant account opens the alerts list, two muted example rules named "Net IV spike" appear, on SPY and QQQ: Net IV Chg beyond plus or minus 30, or Net IV more than one sigma from its 120-day band, with a once-a-day cooldown. They stay off until switched on and count toward the rule limit; a deleted example is never re-seeded.
Premarket Movers and Close Screen
Premarket Movers is sent at 9:05 AM ET to every account with active access, Basic and up, trials included. It lists the top and bottom five names by OI Chg% and by Net IV Chg, for the S&P 500 stocks table and for the ETFs and indices table, each with a weekday-matched sigma and a star on any name that moved on more than one list.
Close Screen is sent in the last 15 minutes of the session, 3:45 PM ET on a normal day, to paid Quant subscriptions only; a trial does not receive it. It lists the tickers whose gamma structure was decisively one-sided, split into long and short gamma boards, and whose Net Flow ran at least one sigma from its time-of-day norm, every leg holding in the same minute for more than 30 of the 45 minutes that end 15 minutes before the close, on at least 25,000 contracts traded in the session. Each row carries its net premium.
Both emails are on by default. The Emails row of the account menu has one switch per email, and every copy carries its own unsubscribe link.
Which plans include it
Metric email alerts need a Flow or Quant plan: Flow includes 10 rules and Quant 25. Rules on DEX, VEX, CEX, Net Premium or Premium Ratio need Quant. The Close Screen email needs a paid Quant subscription. Premarket Movers also reaches Basic and trials: every account with active access gets it.
Related
- Pulse screener: the table whose columns the rules read, and home of the Sustained Flow board.
- Dashboard: the sigma badges that share their 120-day bands with z-score conditions.
- All features, daily emails in the docs, plans and pricing.